
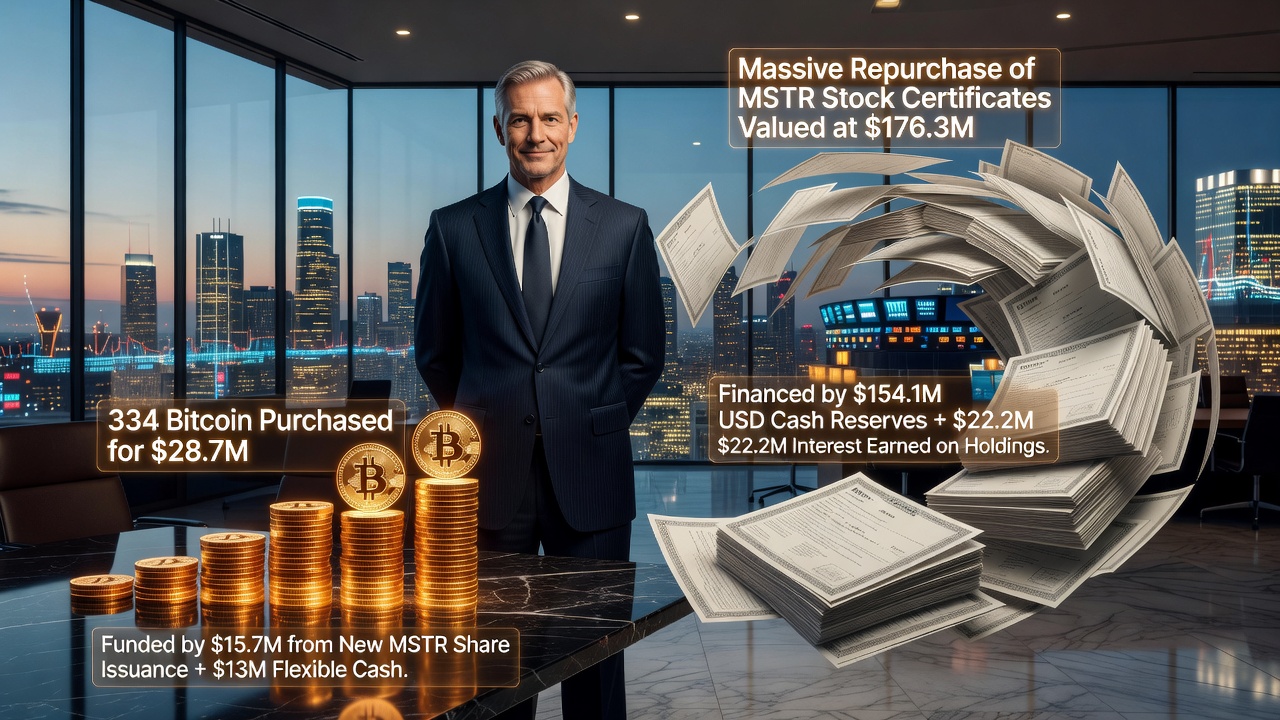
Strategy, the business intelligence company turned corporate Bitcoin accumulator under Michael Saylor, added 334 Bitcoin for roughly $28.7 million last week. On its own, that figure would barely register - it is one of the smaller weekly additions in the company's multi-year buying campaign. The more consequential detail is how the company funded two separate moves at once: buying a small amount of Bitcoin while simultaneously spending over $176 million repurchasing its own shares, MSTR.
A Financing Model Built on Multiple Moving Parts
Strategy's playbook has not resembled a simple "raise cash, buy Bitcoin" operation for a long time. The Bitcoin purchase itself was funded mostly through issuing and selling new MSTR shares - about $15.7 million worth - with a smaller contribution of $13 million coming from the company's flexible USD cash pool. That share issuance represents a form of dilution, the familiar mechanism critics have pointed to for years as a risk embedded in the company's growth strategy.
What stands out this time is the buyback. Strategy funded its $176.3 million MSTR repurchase using $154.1 million from its USD cash reserves and $22.2 million in interest earned on those dollar holdings. That interest detail matters. A company sitting on billions in cash can generate meaningful yield simply by holding it in interest-bearing instruments, similar in principle to how stablecoin issuers earn income on reserves. Seeing that yield redirected into share buybacks, rather than additional Bitcoin purchases, signals a new layer of financial engineering at the company.
Cash Reserves Behind the Strategy
The company's balance sheet now includes several distinct cash buckets, each serving a different function:
- $4.88 billion held as a protected USD reserve
- $833.4 million in flexible USD cash available for near-term use
- A Bitcoin holding built from roughly $64 billion in total purchases, at an average cost basis of $75,440.70 per coin
This structure gives Strategy optionality. It can buy Bitcoin, buy back its own stock, or simply hold cash and earn interest, depending on which move management judges most useful in a given week. That flexibility is itself the story - not any single transaction.
Why Solvency Fears Proved Overblown
For years, skeptics argued that Strategy's debt-fueled Bitcoin accumulation would eventually force a collapse, with forced liquidations driving MSTR toward zero. Those predictions did not account for a basic fact: a company holding tens of billions of dollars in an asset, financed in ways that avoid short-term margin calls, is not structurally equivalent to a leveraged trader facing liquidation risk. That does not mean the strategy is without risk - Bitcoin's price volatility, dilution from share issuance, and the company's heavy correlation to crypto markets remain real factors for anyone evaluating MSTR as an investment.
What It Means Going Forward
If Bitcoin's price continues rising, Strategy will likely remain a reference point in discussions about corporate crypto exposure - both as a case study in financial structuring and as a cautionary example of concentration risk. Investors and analysts watching the company should pay closer attention to how it allocates cash between Bitcoin purchases, buybacks, and interest-generating reserves, since that allocation now says as much about the company's financial strategy as the size of its Bitcoin holdings.